Auto insurance in Massachusetts can feel like a maze of numbers, coverage options, and regulations that often leave drivers scratching their heads. How much is auto insurance in Massachusetts, you ask? Well, strap in for a ride through the essentials of Massachusetts auto insurance, including what you must cover, what you might want, and how much it all might set you back.
In this guide, we’ll navigate the ins and outs of Massachusetts auto insurance with a focus on saving you money while ensuring you’re well-covered. From mandatory coverage laws to tips on scoring the best deals, consider this your insider’s guide to the Bay State’s auto insurance landscape.
Understanding Auto Insurance Basics in Massachusetts
Ever wondered why your auto insurance bill keeps fluctuating? Here’s the deal: Massachusetts has specific requirements that dictate your rates.
Let’s dive into the essentials of auto insurance in this state to help you understand what you’re paying for and why.
Minimum Coverage Requirements
In Massachusetts, you can’t just skip on liability coverage. You’re required by law to have at least $20,000 per person and $40,000 per accident for bodily injury, along with $5,000 for property damage. This is non-negotiable if you want to drive legally here.
Mandatory and Optional Coverages
Here’s the scoop: Aside from the mandatory coverages, you have the option to add extras like collision and comprehensive coverage. These can save you a ton of money if you’re involved in an accident or your car gets stolen.
Pro Tip: Consider adding uninsured motorist coverage. It protects you if you’re hit by someone who doesn’t have insurance. It’s an extra layer of security that’s often overlooked.
Factors Influencing Insurance Rates
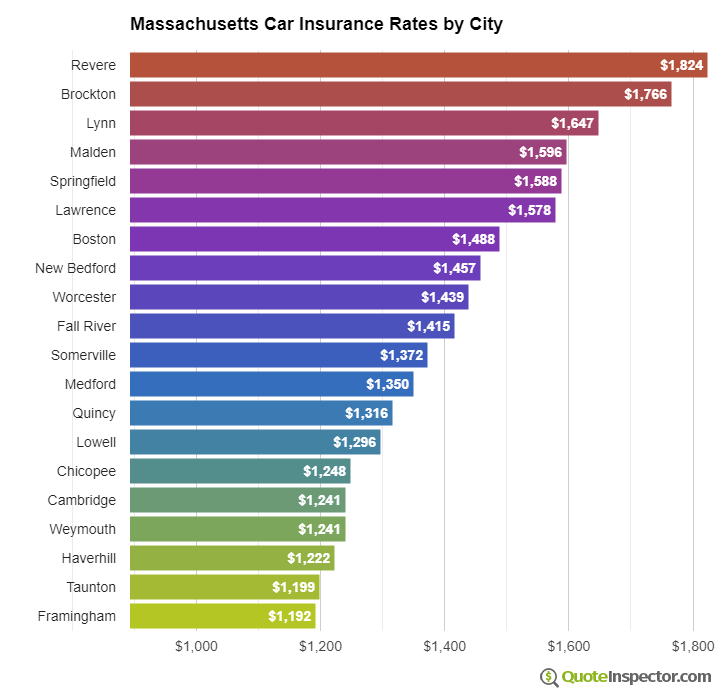
Ever felt like you’re paying more than your friend for the same coverage? That’s because Massachusetts bases rates on a variety of factors, including your driving history, age, and location. Even your car’s make and model can make a significant impact.
Filing an Auto Insurance Claim
Got into a fender bender? Here’s what you do: Report the accident to your insurer ASAP and provide detailed documentation. The process might seem daunting, but Massachusetts has a structured system to ensure claims are handled efficiently.
Remember, the faster you file, the quicker you’ll see your claim settled. Don’t procrastinate!
Cost Factors for Auto Insurance in Massachusetts
Ever wondered why your auto insurance premium seems to be burning a hole in your pocket? You’re not alone. Massachusetts drivers face a unique set of factors that shape how much we end up paying for auto insurance.
Understanding these factors can help you make informed decisions. From your driving history to the type of car you drive, each element plays a role in determining your insurance costs. Let’s dive into the details and see what’s really driving up those premiums.
Key Elements Impacting Premium Costs
The cost of auto insurance in Massachusetts doesn’t just pop out of thin air. It’s calculated based on several important factors. One major factor is your driving history. Have you been in accidents or received speeding tickets? If yes, your premiums might be higher.
- Your vehicle type and age also matter. Flashy, new sports cars? Expect to pay more. Older, reliable sedans? You might save some cash.
- Where you live affects rates too. Think urban vs. rural environments.
Impact of Driving History on Insurance Rates
Here’s the deal: if you’ve been a safe driver, insurers see you as less of a risk. BUT, have a few fender benders on your record? Your rates can skyrocket. In Massachusetts, even a single accident can increase your premium by up to 40%. Now that’s an incentive to keep it clean!
Pro Tip: Take a defensive driving course to potentially reduce your rates.
The Role of Vehicle Type and Age
Not all vehicles are created equal when it comes to insurance. Insurers look at the cost to repair your vehicle and its safety features. A brand-new sports car is more expensive to insure than a five-year-old sedan with top safety ratings. So, the type and age of your car can significantly impact your premiums.
Average Costs for Different Coverage Levels
To give you a clearer picture, here’s a breakdown of average insurance costs based on coverage level, vehicle type, and driving record impact:
| Coverage Level | Average Cost | Vehicle Type | Driving Record Impact |
|---|---|---|---|
| Minimum Coverage | $1,200 | Sedan | Low |
| Full Coverage | $1,900 | SUV | Moderate |
| Premium Coverage | $2,500 | Sports Car | High |
Tips for Finding Affordable Auto Insurance
Ever wondered why your auto insurance bill feels like a car payment? You’re not alone. But here’s the deal: there are ways to slice that premium down to size.
Whether you’re shopping for a new policy or trying to lower your current rate, understanding a few key strategies can put cash back in your pocket. Let’s dive into how you can find more affordable auto insurance in Massachusetts.
Strategies to Reduce Auto Insurance Premiums
First things first, if you want to lower your premiums, consider raising your deductible. Sounds counterintuitive, right? BUT, a higher deductible can significantly reduce your monthly payments.
Another method? Drive less. If you can cut down on your mileage, many insurers will reward you with reduced rates. It’s all about the risk they’re taking on, and lower mileage means less risk.
The Advantages of Bundling Insurance Policies
Insurance companies love it when you bundle. Why? Because it means more business for them. BUT, here’s the kicker—bundling different types of insurance, like home and auto, can seriously slash your rates.
According to the Insurance Information Institute, you could save up to 15% by bundling your policies. It’s a win-win because it simplifies your bills and reduces your overall costs.
Methods to Qualify for Discounts on Car Insurance
Think you don’t qualify for discounts? Think again. Ask your insurer about discounts for safe driving, being a good student, or even for your profession. You’d be surprised how many discounts are out there.
Pro Tip: Install safety features like anti-theft devices. Some insurers will give you a break on your premium just for making your car harder to steal.
The Importance of Comparing Multiple Insurance Quotes
When was the last time you compared insurance quotes? If it’s been a while, you’re likely overpaying. Insurers constantly adjust their rates, and what was a good deal last year might not be the best now.
Use comparison sites to get quotes from multiple insurers. This process can feel tedious, BUT trust me, it’s worth every penny you save.
Regional Insurance Providers and Options
How many times have you felt overwhelmed by the dizzying array of auto insurance choices? You’re not alone. Choosing the right auto insurance provider in Massachusetts can feel like navigating a labyrinth.
But here’s the deal: knowing your regional options can streamline your decision-making process and potentially save you a bundle. Massachusetts offers a variety of auto insurance providers, from national giants to local gems, each with its own set of perks.
Popular Auto Insurance Providers in Massachusetts
When it comes to insuring your ride in Massachusetts, some providers consistently get the spotlight. Liberty Mutual and Geico are national heavyweights that dominate the landscape. However, don’t overlook local players like Plymouth Rock Assurance and MAPFRE Insurance.
Why does this matter? Local companies often offer personalized service and an intimate understanding of the state’s regulations.
- Liberty Mutual – Known for comprehensive coverage and various discount options.
- Geico – Popular for competitive rates and strong online services.
- Plymouth Rock Assurance – Offers unique programs like the “Door to Door Valet Claim Service”.
- MAPFRE Insurance – Known for excellent customer support and regional expertise.
Benefits of Choosing Local vs. National Insurance Companies
Ever wondered whether going local could give you an edge? The benefits are real. Choosing a local insurance company can lead to more personalized service and a better grasp of local driving conditions and laws.
BUT national companies come with their own advantages, like broad coverage options and extensive resources.
Pro Tip: Don’t just look at the price. Consider customer service and the claims process as vital factors.
Unique Insurance Options Specific to Massachusetts
Massachusetts isn’t just any state when it comes to auto insurance. It offers some unique options that you won’t find elsewhere.
For instance, the state’s Personal Injury Protection (PIP) is a must-have, covering medical expenses regardless of who caused the accident. Additionally, “No Fault” insurance is designed to reduce litigation costs and expedite claim settlements.
Comparison of Top Providers
Here’s a quick look at how the top providers in Massachusetts stack up:
| Provider | Coverage Options | Customer Service Rating | Average Cost |
|---|---|---|---|
| Liberty Mutual | Comprehensive, Collision, PIP | 4.2/5 | $1,500/year |
| Geico | Liability, Uninsured Motorist | 4.0/5 | $1,200/year |
| Plymouth Rock Assurance | Comprehensive, Roadside Assistance | 4.3/5 | $1,400/year |
| MAPFRE Insurance | Collision, PIP, Rental Coverage | 4.5/5 | $1,450/year |
Remember, choosing the right provider can make a huge difference—both in your wallet and on the road.
Legal and Regulatory Aspects of Auto Insurance
Think you’re covered just because you have auto insurance? Think again. In Massachusetts, state-specific regulations could impact your coverage more than you realize.
Massachusetts requires every motorist to carry a certain level of auto insurance. But what exactly does that mean for you? Let’s break it down into bite-sized pieces.
Insurance Requirements for Massachusetts Motorists
In Massachusetts, drivers must have a minimum coverage of 20/40/5, which stands for $20,000 for injury per person, $40,000 for total injuries per accident, and $5,000 for property damage. Also, you need coverage for uninsured motorists. Basically, if you’re driving without meeting these standards, you’re living on the edge!
Penalties for Driving Without Insurance
So you forgot to renew your policy? That’s going to hurt. Driving without insurance in Massachusetts can land you a $500 fine and even a year in jail. Plus, there’s the added bonus of having your license suspended. The stakes are high, so make sure you’re covered.
Recent Changes in Insurance Laws
The insurance world is always changing, and Massachusetts is no exception. Recently, the state introduced laws focusing on telematics, which means using technology to track your driving habits. These laws can influence your premiums based on real-time driving data. So, if you’re a safe driver, this could be your golden ticket!
Understanding Consumer Rights
Did you know you have rights as an auto insurance consumer in Massachusetts? You’re entitled to full disclosure of all policy terms, and you can shop around for the best rates without being penalized. Know your rights, and don’t settle for less than you deserve.
Pro Tip: Always read the fine print in your policy. It could save you from unexpected expenses later.
The Future of Auto Insurance in Massachusetts
Did you know that only about 50% of drivers understand the impact of technology on their insurance premiums? The future of auto insurance in Massachusetts is being shaped by rapid innovations and advancements.
Auto insurance isn’t just about premiums anymore. It’s about how technology, environmental concerns, and new models are reshaping the landscape. Let’s dive into the trends and shifts you need to watch.
Trends and Innovations in the Auto Insurance Industry
The auto insurance industry in Massachusetts is undergoing a transformation. Telematics and AI are becoming game-changers. They help insurers assess risk more accurately and offer personalized premiums. Massachusetts drivers are increasingly leveraging these technologies for better rates and safety insights.
The Impact of Technology on Insurance Processes
From mobile apps to AI-driven claims processing, technology is streamlining everything. Faster claims and enhanced customer experiences are now the norm. Insurers are using big data to predict risks, personalize plans, and improve customer satisfaction. The goal? A frictionless and intuitive insurance experience.
Environmental Factors Influencing Policy Adjustments
With climate change impacting weather patterns, insurers are rethinking policies. More frequent and severe weather events mean higher risks. Massachusetts insurers are now adjusting policies to accommodate these environmental shifts. Expect increased focus on coverage for weather-related damages.
Shifts Towards Usage-Based Insurance Models
Traditional insurance models are getting a facelift. Welcome to usage-based insurance (UBI). It lets drivers pay premiums based on how much they drive or how safely they drive. Sensors and telematics devices gather this data, offering a fair and customized rate.
Pro Tip: If you’re a safe driver, consider switching to a usage-based policy to potentially save big on your premiums.
Last Word
Wrapping up our journey through the auto insurance world in Massachusetts, it’s clear that understanding your options and requirements is key to making informed decisions. Keeping an eye on costs while ensuring solid coverage can save you headaches down the road. Remember, whether it’s grasping the basics or diving into future trends, knowledge is your best policy when it comes to auto insurance.
FAQ
What are the minimum auto insurance requirements in Massachusetts?
Massachusetts requires minimum coverage for bodily injury, personal injury protection (PIP), uninsured motorist protection, and property damage.
How do driving history and vehicle type affect insurance rates?
Safe driving records and vehicles with high safety ratings typically result in lower insurance premiums.
How can I reduce my auto insurance premiums?
Consider bundling policies, maintaining a clean driving record, and seeking discounts based on safety features or low mileage.
Are there penalties for driving without insurance in Massachusetts?
Yes, driving without insurance can result in fines, license suspension, and increased insurance premiums once coverage is obtained.
Why is it important to compare multiple insurance quotes?
Comparing quotes ensures you get the best coverage for your needs at the most competitive price.
What trends are impacting the future of auto insurance in Massachusetts?
Technology advancements and environmental considerations are influencing policy options and insurance models.
What are some popular auto insurance providers in Massachusetts?
Popular providers include Liberty Mutual, Plymouth Rock, and MAPFRE Insurance, among others.
